••
Parliament approves external auditor for Auditor-General's Office
•2 min read•1 source
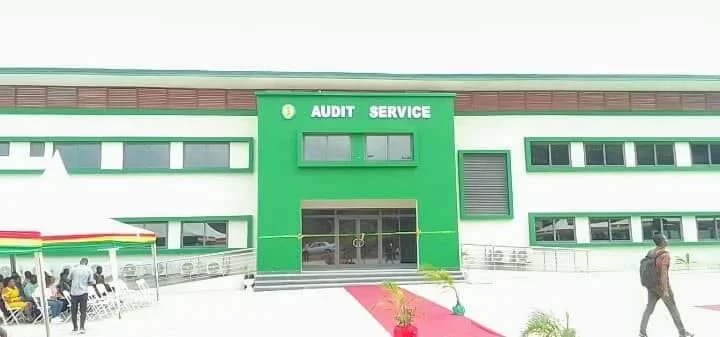
Parliament has approved the appointment of an external auditor to independently review the financial records of the Auditor-General’s Office. This decision, reached on November 3, 2026, follows the adoption of a committee report recommending the move. The measure is designed to ensure that the institution responsible for auditing all public accounts in Ghana is itself subject to rigorous financial oversight, maintaining the integrity of the nation's fiscal monitoring systems.
The appointment is grounded in the legal framework of the 1992 Constitution, specifically Article 187. This constitutional provision mandates that the accounts of the Auditor-General must be audited by an independent body or individual appointed by Parliament. By activating this requirement, the legislature aims to reinforce the principles of accountability and transparency within public financial management, ensuring no state institution operates without scrutiny.
While the motion to appoint an external auditor has been passed, the specific firm or individual tasked with the audit has not yet been named. Parliament is expected to proceed with a formal selection process in accordance with established constitutional and procurement requirements. This oversight mechanism is seen as a crucial step in maintaining public trust, as it subjects the nation's primary auditing body to the same standards of fiscal discipline it applies to other state agencies and departments.
This initiative highlights the importance of checks and balances within Ghana’s governance structure. By ensuring the Auditor-General’s Office remains accountable for its own financial conduct, Parliament seeks to strengthen the overall credibility of the state's financial reporting system. The forthcoming audit will provide a comprehensive assessment of the office's expenditure and management practices, further entrenching transparency across the public sector.


