••
John Abdulai Jinapor announces $3.5bn upstream petroleum investment
•2 min read•2 sources
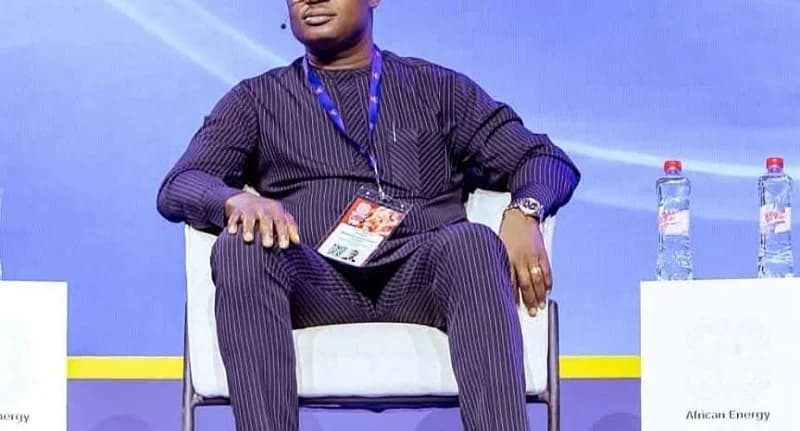
The Minister for Energy and Green Transition, Dr. John Abdulai Jinapor, has announced that Ghana has secured US$3.5 billion in investment commitments for its upstream petroleum sector. Speaking at the African Energy Week in Cape Town, South Africa, the Minister revealed that these funds are specifically earmarked for expanding existing operations and drilling new oil wells across the country's offshore basins. The announcement signals a significant boost for the industry as the government seeks to reverse declining production trends.
Dr. Jinapor attributed the influx of capital to the government's sustained efforts to restore investor confidence through comprehensive legal and fiscal reforms. These measures are designed to create a more stable and attractive environment for international oil companies to commit long-term resources. The Minister emphasized that the multi-billion-dollar commitments are a direct result of ongoing engagement with industry stakeholders and a clear policy direction established under the leadership of President John Dramani Mahama.
Beyond exploration and production, the Minister underscored the strategic importance of domestic value addition. He stated that the government is prioritizing the local refining of crude oil to support industrialization and enhance national energy security. By processing petroleum resources within Ghana, the administration aims to stimulate job creation and reduce the country's reliance on imported refined products, which is expected to stabilize the local economy.
This investment drive represents a central pillar of Ghana's strategy to maximize its natural resource potential for national development. Dr. Jinapor expressed the government's determination to ensure that these investments translate into tangible benefits for the Ghanaian people, reaffirming a commitment to transparency and sustainable development in the management of the nation's petroleum wealth as new wells begin to come online.
Live rates
Dollar to cedi rate →

